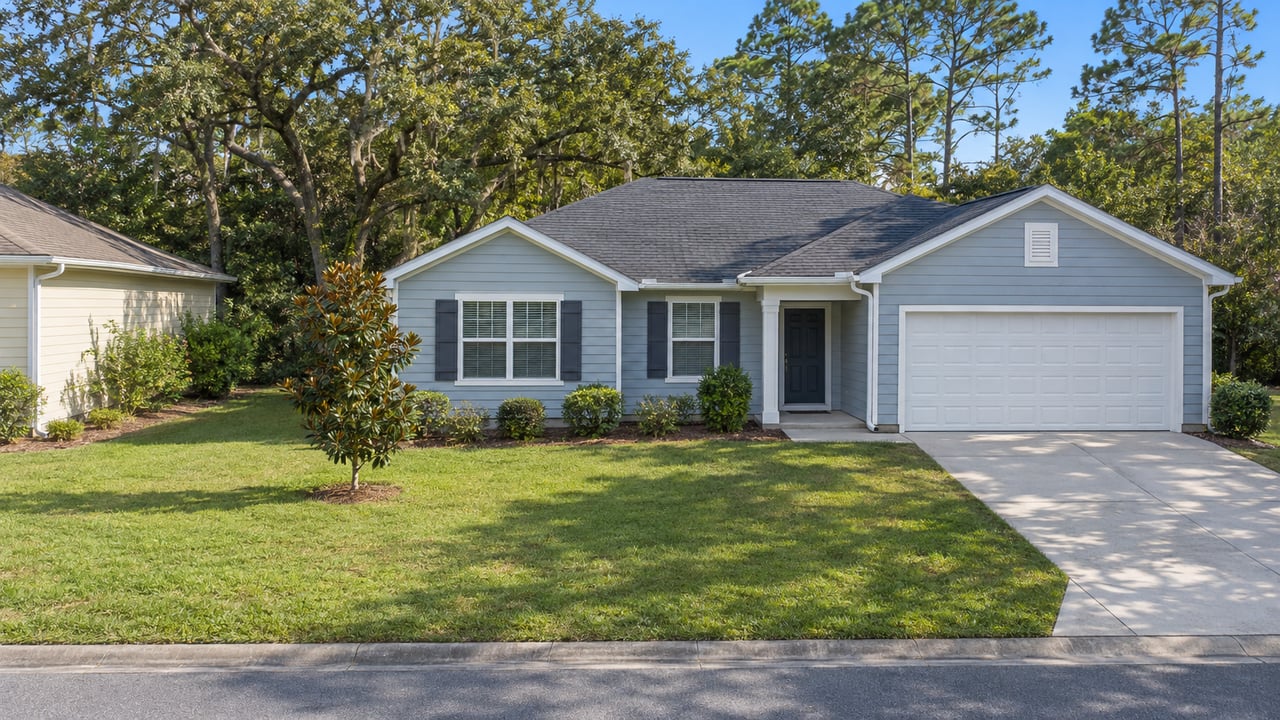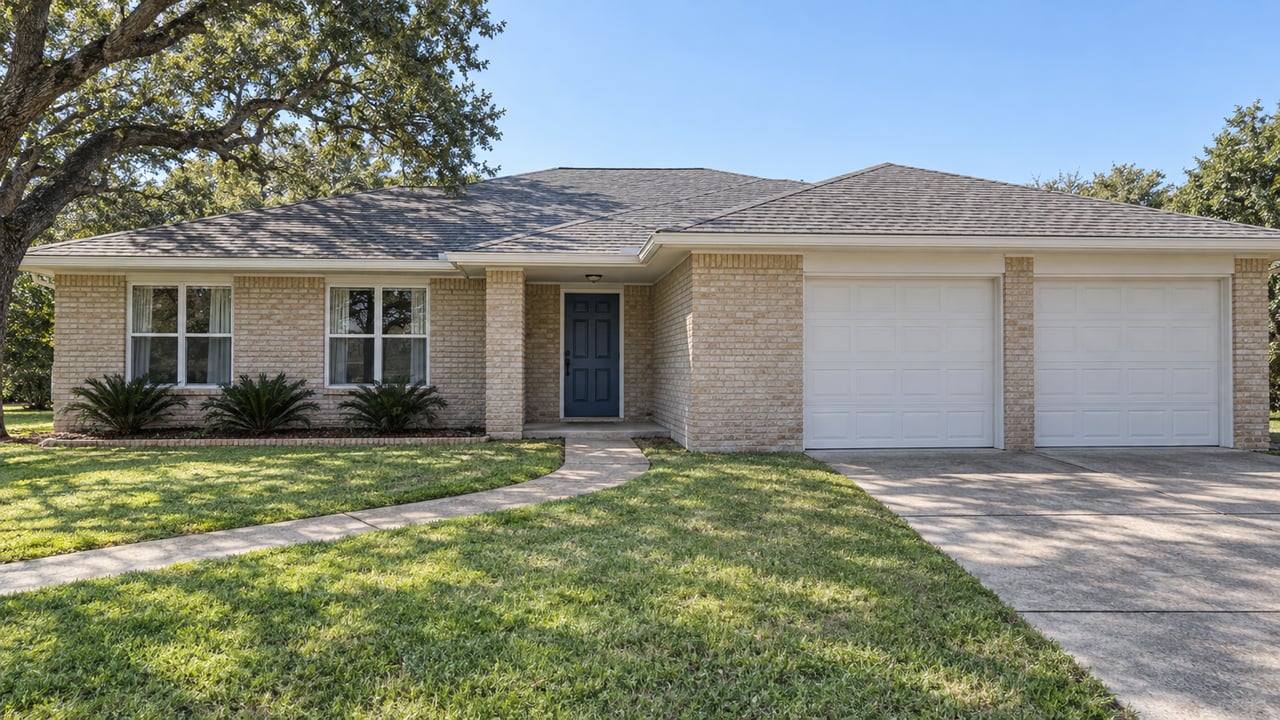
If you are listing a resale home in SweetBay this fall, one of your biggest competitors is a mortgage rate. Harris Doyle Homes builds Indigo Lakes, which SweetBay calls its latest phase, and is advertising "Up to $30K Incentive or 3.49% Rate." In the week ending October 29, 2026, the national average 30-year fixed rate in Freddie Mac's Primary Mortgage Market Survey was 7.24%. That puts 3.75 percentage points between the builder's headline and the market average, and a buyer touring your house has probably already seen the sign.
A resale seller can try to answer with a concession.
What the builder is putting in front of your buyer
Harris Doyle's SweetBay sales office is at 1425 Buttonsage Avenue. Its plans run from 2 to 6 bedrooms and 1,167 to 3,307 square feet, with list prices starting at $344,600. Quick move-in homes range from $399,473 for a 2-bedroom Thatch to $726,189 for the 6-bedroom Santa Rosa at 1445 Tulip Ct. Some of them carry "$30K Incentive or 2/1 Buydown." Others, such as 1453 Tulip Ct, carry "$30K Incentive or 3.49% Rate."
There are more layers. Presale contracts carry a separate $20,000 "use as you choose" incentive that requires financing with Silverton Mortgage and has exclusions. The builder's financing page also advertises up to $7,500 toward closing costs for buyers who finance with Silverton, which it calls its preferred lender.
A resale listing has to compete with the builder's advertised incentives and rate.
Seller and builder contributions
Fannie Mae's Selling Guide calls these payments interested party contributions. It names both "the property seller" and the "builder/developer" as interested parties. Freddie Mac's Guide lists the builder, developer, property seller and real estate agent the same way.
What a 2/1 buydown means
In a standard 2/1 buydown, the effective rate is 2 points below the note rate in year one and 1 point below in year two. After that the full note rate applies.
Harris Doyle's SweetBay community page shows the 3.49% rate without an APR, rate type, buydown term, loan program or expiration date, and its quick move-in listings describe their payment figures as "not an offer for a loan." The note rate, the APR, how long any reduced rate lasts and which loan program it requires are the terms a buyer gets in writing from a lender before comparing that offer with your price.
Where this leaves a resale listing
The resale seller's strongest lever is usually the price and the house itself. In September 2026, the Panama City metro area, which Florida Realtors defines as Bay and Gulf counties, recorded 378 single-family closed sales, up 8.9% from a year earlier, at a median price of $367,959, up 2.5%. Those figures come from the Florida Realtors September 2026 metro summary. They cover a wider area than SweetBay, but they show sales volume rising even with rates above 7%.
The neighborhood around both kinds of homes keeps filling in. Jeremiah's Italian Ice lists its SweetBay location at 950 Promenade St., Suite E. In March, the Panama City News Herald reported that city commissioners unanimously approved the SweetBay Town Center Phase 3 conceptual plan for 928 Promenade St., which sets up infrastructure for a third phase of commercial development.
Before a resale seller decides on a concession, and before a buyer compares offers, these are the questions to put to a lender:
- Is the advertised rate fixed or adjustable, and is it permanent or temporary?
- What is the note rate, and what does the payment look like after any buydown period ends?
- Which loan program does the offer require, and does it require a specific lender?
- What APR goes with the rate?
- On a resale, what LTV will the buyer have, and what concession cap applies at that LTV?
If you're preparing a SweetBay resale with Indigo Lakes inventory nearby, Think Real Estate can help you set a price. Contact a Local Expert before you list.